
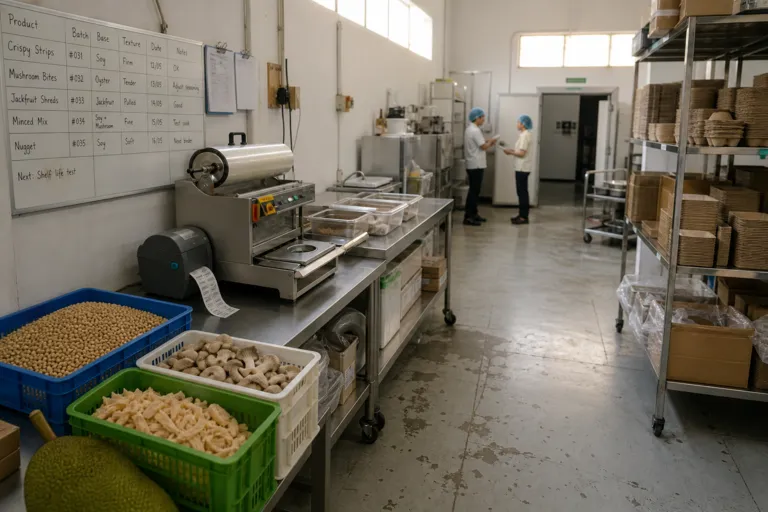
Vietnam has long had everyday plant-based staples. One regional view frames tofu in Vietnam as a cultural constant rather than a passing wellness trend. What looks different now is commercialization. Multiple Vietnam-focused sources describe growth drivers tied to health consciousness, environmental and animal welfare concerns, and shifting preferences. The numbers show why brands are watching the Vietnam plant-based food market closely: IMARC values Vietnam’s vegan food market at USD 111.6 million in 2025 and projects it to reach USD 223.4 million by 2034, at a CAGR of 8.02% during 2026–2034.
Other Vietnam estimates align on direction even when endpoints differ. Ascentium projects the vegan food market in Vietnam to grow at a CAGR of 8.1%, reaching USD 220.5 million by 2033, and links this to advancements in food technology that make plant-based meat and dairy alternatives more accessible. B-Company adds important context on scale: it says the vegan food market accounts for less than 1% of total F&B revenue, and cites a value of nearly US$112 million in 2025, while noting a CAGR of 8% over the next decade. That combination supports a clear story: fast growth, small base.
What “Ready to Scale” Looks Like in Vietnam’s F&B Reality
Scaling also depends on distribution and on where consumers actually eat. Ascentium estimates Vietnam’s food service market at about USD 24.77 billion in 2025, projecting a CAGR of 10.73% to around USD 41.22 billion by 2030. It also cites over 323,000 F&B establishments entering 2025, highlighting a fragmented but dynamic channel landscape. These figures matter for plant-based brands because availability is a key adoption lever. IMARC specifically points to expanding availability of plant-based meat alternatives, supported by digital influence and innovation, and notes social platforms such as TikTok, Instagram, and YouTube as demand accelerators through recipes and lifestyle content.
Demand indicators are not limited to sales forecasts. B-Company reports a Statista-based online survey of 2,757 people aged 16 and over in which 45% said they had eaten plant-based food several times a week, often for health, religion, or to “feel lighter.” Vietnam’s tradition of eating vegan on specific lunar calendar days also supports a baseline openness, even among people who are not fully vegetarian. At the same time, the same source flags friction points that can slow scaling, including the lack of an official legal definition that can create trust issues unless managed through rigorous certification.
Finally, scale is constrained or enabled by production, logistics, and product-market fit. Ken Research cites “48.6 million metric tons” for Vietnam in 2025 and argues that volume scale can support plant utilization and supplier bargaining, but that gains depend on reducing post-harvest and cold-chain losses. It also points to capacity-building signals, including a Ha Nam food plant representing approximately USD 90 million (2024 announcement, Vietnam), plus JBS announcing USD 100 million (2025, Vietnam) for two meat-processing plants—investments that can create opportunities in cold storage, packaging, food safety services, and protein distribution. On product fit, B-Company notes that Western-style plant-based items like patties and sausages can have limited appeal compared with products adapted to local cuisine, because consumers prefer textures and flavors that work in dishes such as Banh Mi, Pho, or Hot Pot.
How big is Vietnam’s vegan food market, and how fast is it projected to grow?
Is the plant-based segment still small inside Vietnam’s wider F&B industry?
What evidence suggests frequent consumer engagement with plant-based food in Vietnam?
What makes scaling the Vietnam plant-based food market harder than just forecasting growth?
What supply-side signals point to improving capacity and distribution infrastructure?